MergerWaterfallStart modeling free
Why Merger Waterfall01 · Deal terms, made clear

Turn each term into dollars, holder by holder.

Liquidation preferences, participation, escrow and earnouts are written for lawyers. Merger Waterfall reads them from the charter and the cap table and shows, in dollars, what each one means for each shareholder.

Distribution · Present
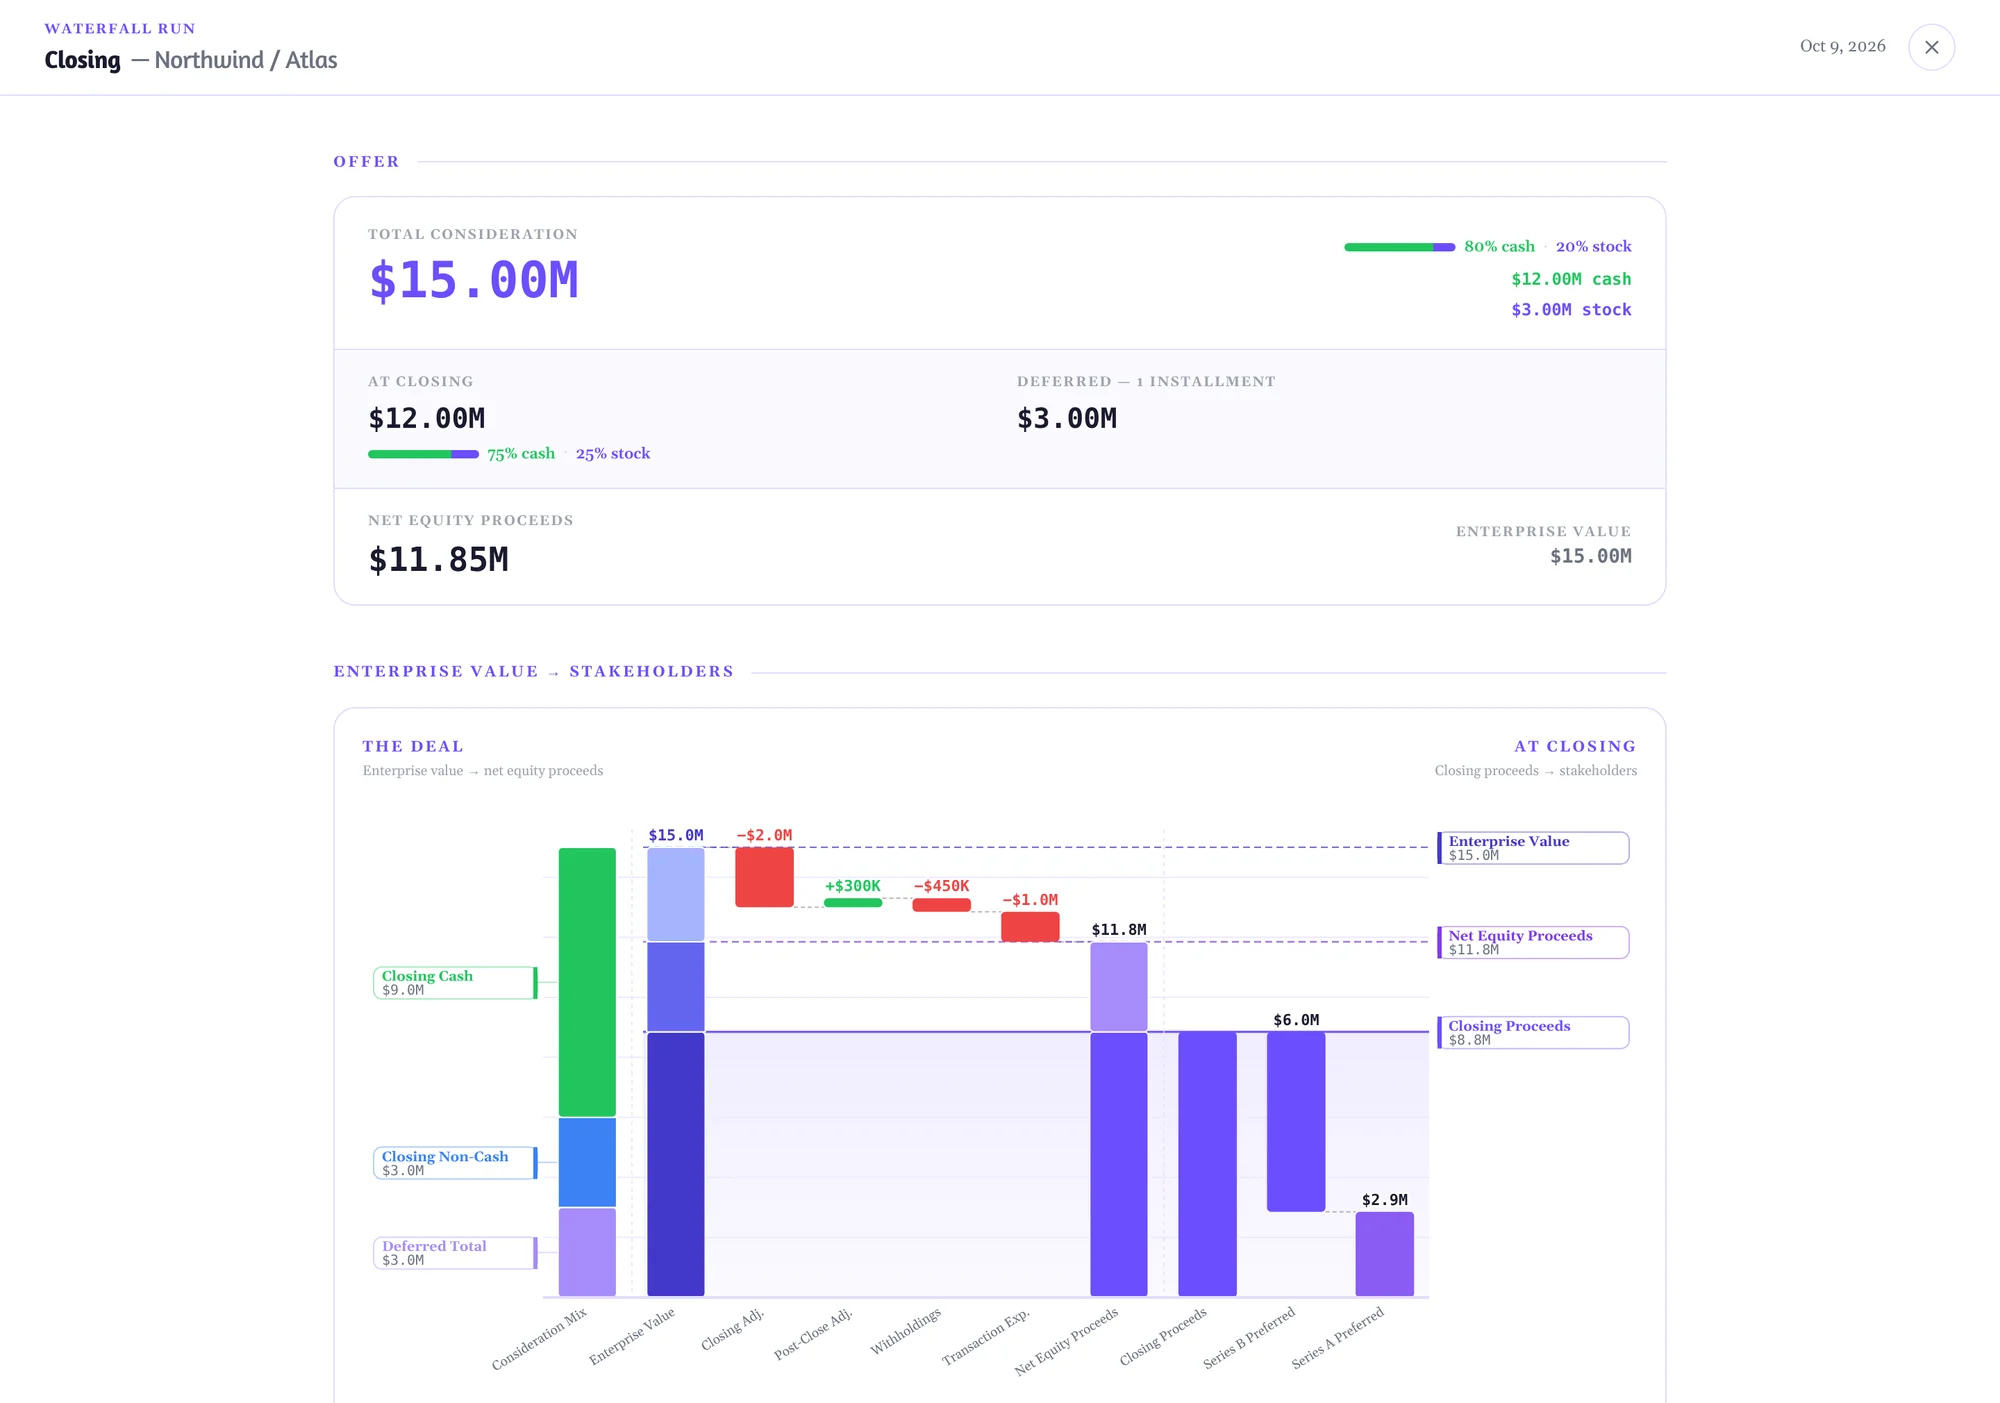
Studio's presentation view of the Closing run: $15.00M total consideration, $11.85M net equity proceeds, and a waterfall chart running from enterprise value through deductions to the Series B and Series A payouts.

“Nobody can tell me what this term means for my check.”

Who it's for

The same problem, asked three ways.

Sell-side advisors

Bankers, M&A advisors, fractional CFOs

“How do I show the board what this offer is really worth to common?”

One picture from headline price to each class, ready for the board deck.

Company counsel

Deal and venture attorneys for the company

“My client needs to understand the preference stack before we mark it up.”

Each term listed with the section it came from, and its dollar effect.

The company

Founders, the CFO, the board, employees

“What do I actually walk away with, and when?”

Your own number, at closing and in total, on a private link.

Why use Merger Waterfall for this

What you see in the product.

01

Every term traced to its clause

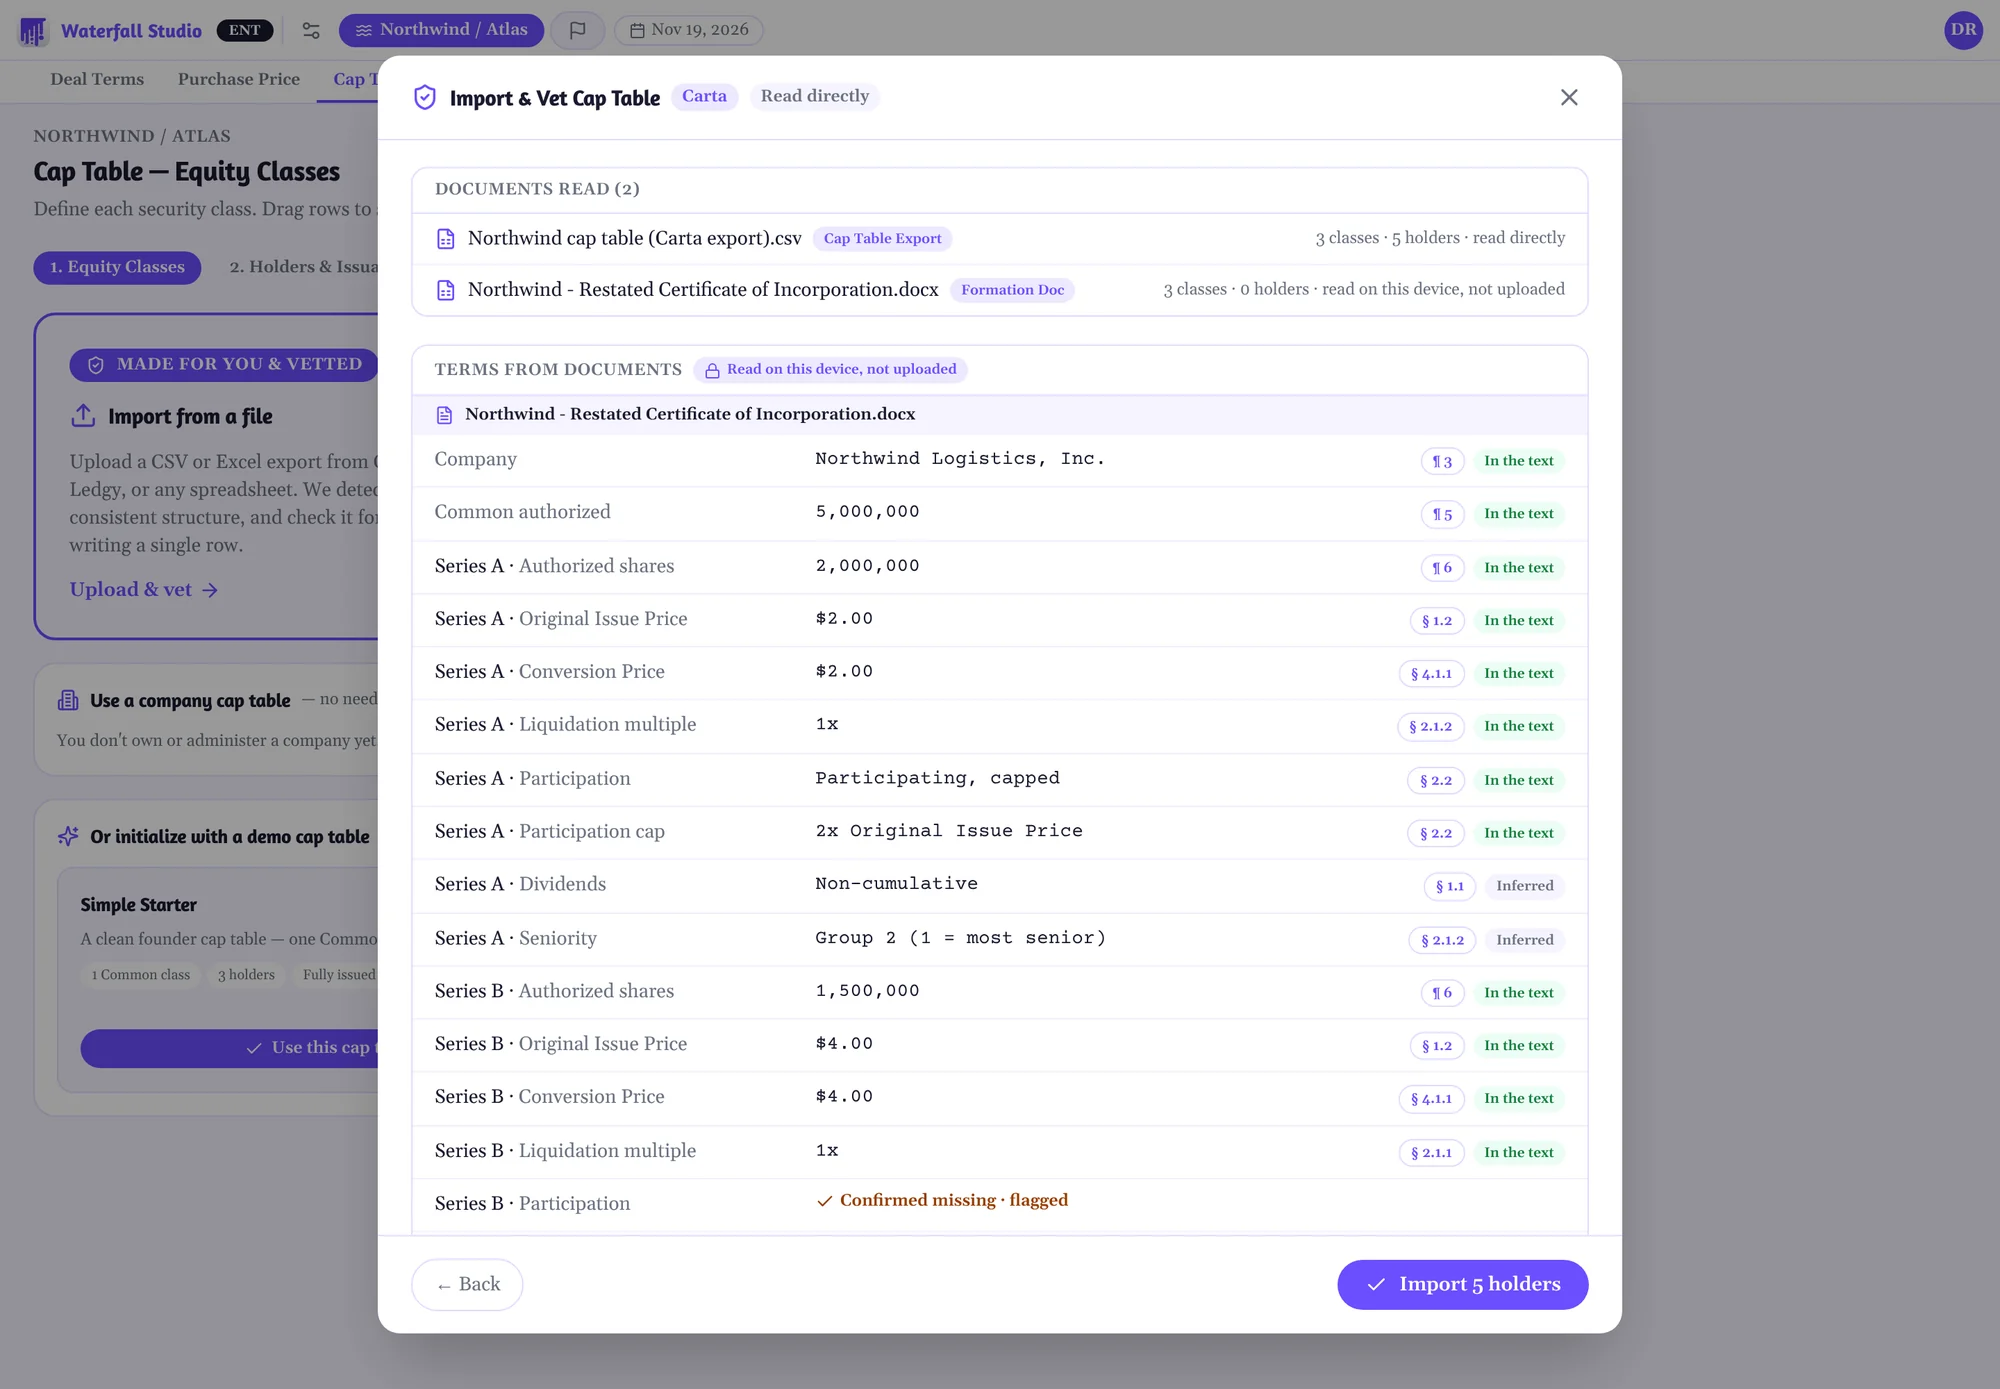
Studio reads the certificate of incorporation and the cap table export and lists each term with the section it came from. Anything the document does not state is flagged, never guessed.

  • Section reference on every term
  • “In the text” and “Inferred” labeled apart
  • Missing terms become deal flags
Cap Table · Terms from documents
The 'Terms from documents' review: Series A and Series B terms each with a section reference such as § 2.1.2 and a label 'In the text' or 'Inferred'. Series B participation reads 'Confirmed missing · flagged'.

02

The whole deal on one axis

Price, deductions, net proceeds and each class's payout on a single shared scale. Closing and deferred money are kept visibly apart, so nobody mistakes the headline for the wire.

  • Consideration mix: cash, stock, escrow, earnout
  • Purchase-price bridge to net equity proceeds
  • Payout by class, senior to junior
Distribution · Present
Studio's presentation view of the Closing run: $15.00M total consideration, $11.85M net equity proceeds, and a waterfall chart running from enterprise value through deductions to the Series B and Series A payouts.

03

Each holder sees their own number

A fenced link shows one stakeholder their proceeds and nothing about anyone else. The fence is applied on the server, so other holders never reach the browser.

  • One stakeholder per link
  • Expiry, optional password, view log
  • No account needed to read it
Share link · one stakeholder
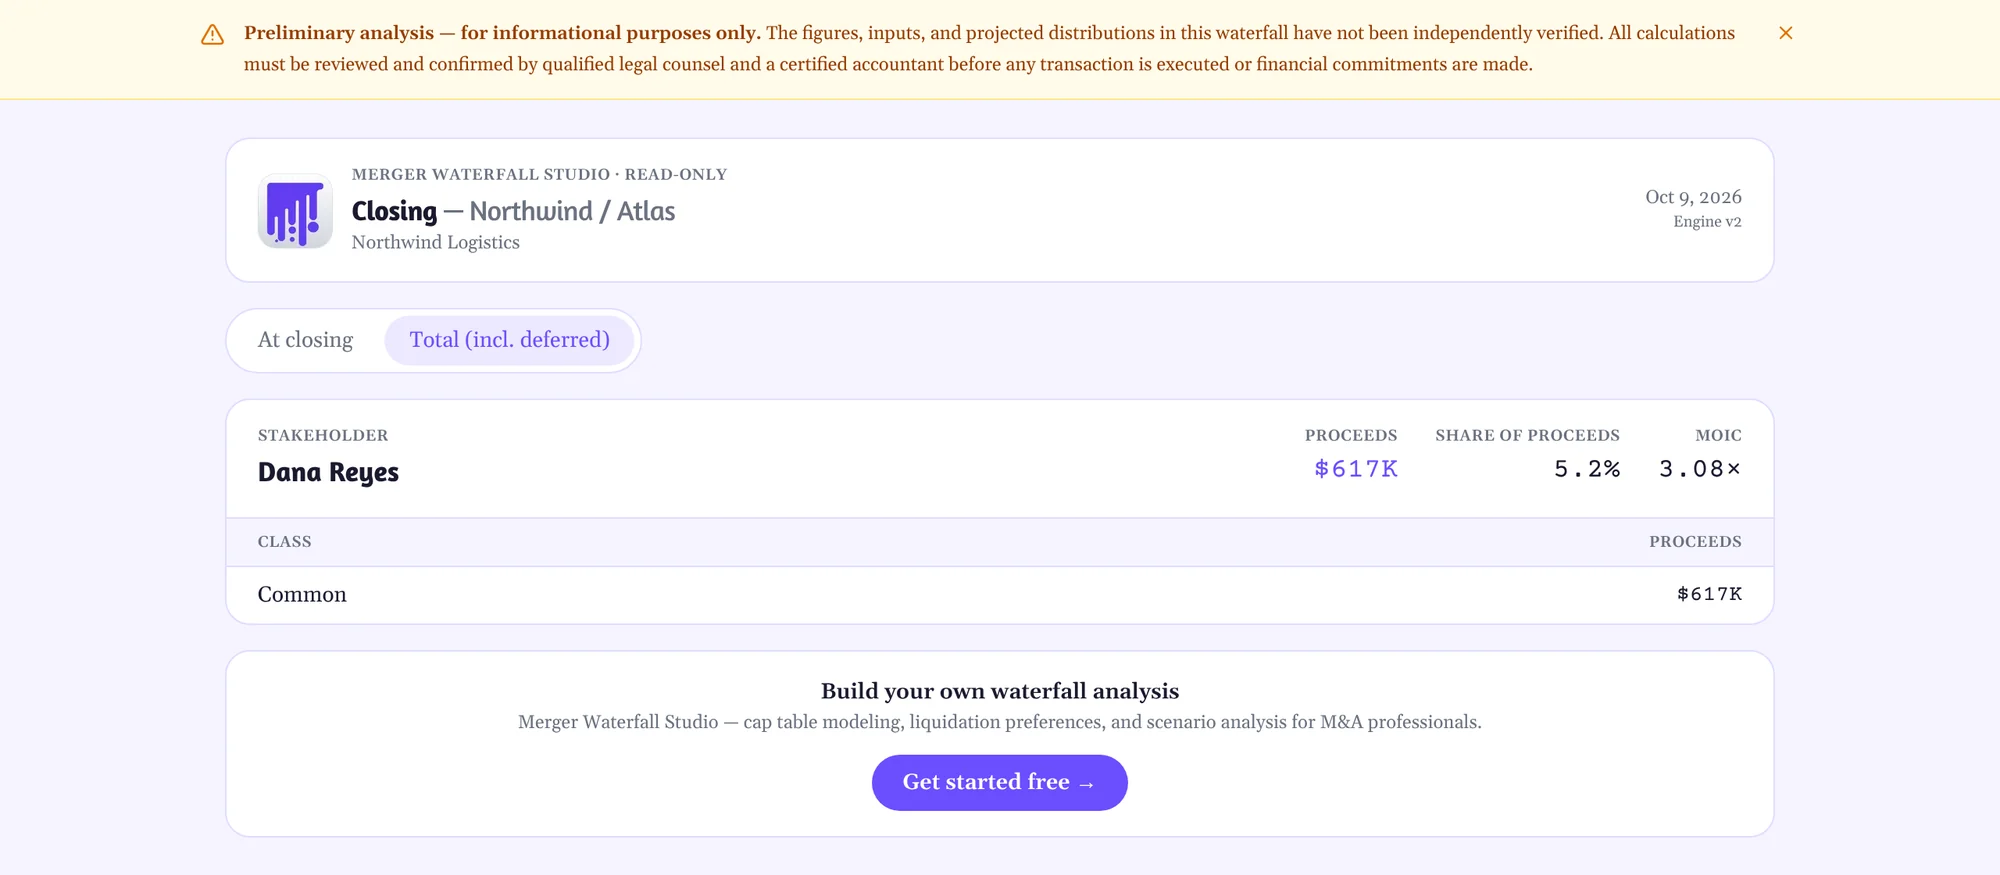
A fenced share link showing only Dana Reyes: $617K in proceeds, 5.2% of proceeds, 3.08x MOIC, from Common.

Deal scenarios

Where this comes up, with the numbers.

Each scenario changes one thing on the Northwind / Atlas demo deal and shows what every holder receives before and after. Computed by the same engine Studio runs.

Scenario 1Any timeDemo · Northwind / Atlas

What would a sale actually pay us?

What changed
Same cap table, same deal costs, four headline prices
Usually raised by
Founders and boards, long before any buyer calls

At $11M the founders receive nothing. At $15M Dana receives $617k. At $25M, $3.95M. The preferences take the first $10M of equity value, so the founders' outcome is not proportional to the price.

Holder$11.0M sale$14.0M sale$15.0M sale$25.0M sale
Meridian Ventures II

Series B lead

$6.00M$6.00M$6.00M$6.00M
Cardinal Capital

Series A fund

$1.85M$4.21M$4.46M$6.96M
Dana Reyes

Founder · CEO

—$283k$617k$3.95M
Sam Okoro

Founder · CTO

—$213k$463k$2.96M
Employee RSAs

Common pool

—$70.83k$154k$988k
Option Holders

ITM options

—$70.83k$154k$988k
Net equity proceeds$7.85M$10.85M$11.85M$21.85M

Why: Series B and Series A hold $10M of liquidation preferences that are paid before common. Below that line every dollar goes to the investors; above it, common shares the rest.

Computed by the Merger Waterfall engine · every column ties to its proceeds

Scenario 2FinancingDemo · Northwind / Atlas

The new investor wants a 1.5x preference. What does that cost us later?

What changed
Series B liquidation preference 1.0x → 1.5x
Usually raised by
An investor, in a financing or a bridge, months before any sale

In a $15M sale, a 1.5x Series B preference takes everything that would have gone to common: Dana's $617k becomes $0, and every employee holder is wiped out too.

HolderSeries B at 1.0xSeries B at 1.5xChange
Meridian Ventures II

Series B lead

$6.00M$9.00M+$3.00M
Cardinal Capital

Series A fund

$4.46M$2.85M−$1.61M
Dana Reyes

Founder · CEO

$617k—−$617k
Sam Okoro

Founder · CTO

$463k—−$463k
Employee RSAs

Common pool

$154k—−$154k
Option Holders

ITM options

$154k—−$154k
Net equity proceeds$11.85M$11.85M—

Why: The extra 0.5x adds $3M to the most senior claim. Series B and Series A then need $13M, more than the $11.85M available.

Computed by the Merger Waterfall engine · every column ties to its proceeds

Scenario 3FinancingDemo · Northwind / Atlas

If we push back on Series A participation, how much do we get back?

What changed
Series A: participating, capped at 2.0x → non-participating
Usually raised by
Company counsel, marking up the investor's terms

Removing Series A participation moves $463k from Cardinal Capital to common. Dana's proceeds rise from $617k to $822k.

HolderParticipating, 2.0x capNon-participatingChange
Meridian Ventures II

Series B lead

$6.00M$6.00M—
Cardinal Capital

Series A fund

$4.46M$4.00M−$463k
Dana Reyes

Founder · CEO

$617k$822k+$206k
Sam Okoro

Founder · CTO

$463k$617k+$154k
Employee RSAs

Common pool

$154k$206k+$51.39k
Option Holders

ITM options

$154k$206k+$51.39k
Net equity proceeds$11.85M$11.85M—

Why: Non-participating preferred takes its preference or its as-converted share, not both. At this price Series A keeps its $4M preference and stops sharing in the rest.

Computed by the Merger Waterfall engine · every column ties to its proceeds

Scenario 4Signing → closingDemo · Northwind / Atlas

How much of our money is actually paid at closing?

What changed
$1.5M escrow and $1.5M earnout withheld; only closing proceeds distributed
Usually raised by
Founders and the board, reading the consideration mix

Every dollar the founders receive depends on the escrow and earnout. If neither releases, $8.85M is distributed and common receives $0.

HolderAll consideration paidClosing onlyChange
Meridian Ventures II

Series B lead

$6.00M$6.00M—
Cardinal Capital

Series A fund

$4.46M$2.85M−$1.61M
Dana Reyes

Founder · CEO

$617k—−$617k
Sam Okoro

Founder · CTO

$463k—−$463k
Employee RSAs

Common pool

$154k—−$154k
Option Holders

ITM options

$154k—−$154k
Net equity proceeds$11.85M$8.85M-$3.00M

Why: Closing proceeds of $8.85M cover Series B's $6M and part of Series A's $4M preference. Common is paid only from the deferred $3M.

Computed by the Merger Waterfall engine · every column ties to its proceeds

Try it on your next deal.

Bring the cap table export and the charter. Leave with a distribution spreadsheet you can hand to the board, the buyer and the auditor.