MergerWaterfallStart modeling free
Why Merger Waterfall02 · Negotiations, visualized

Watch the payouts move as the terms move.

Every turn of a negotiation changes who gets paid what. Merger Waterfall keeps a version for each turn, so you can show the effect of a price change, a new preference or a bigger holdback the same day it is proposed.

Distribution · Runs
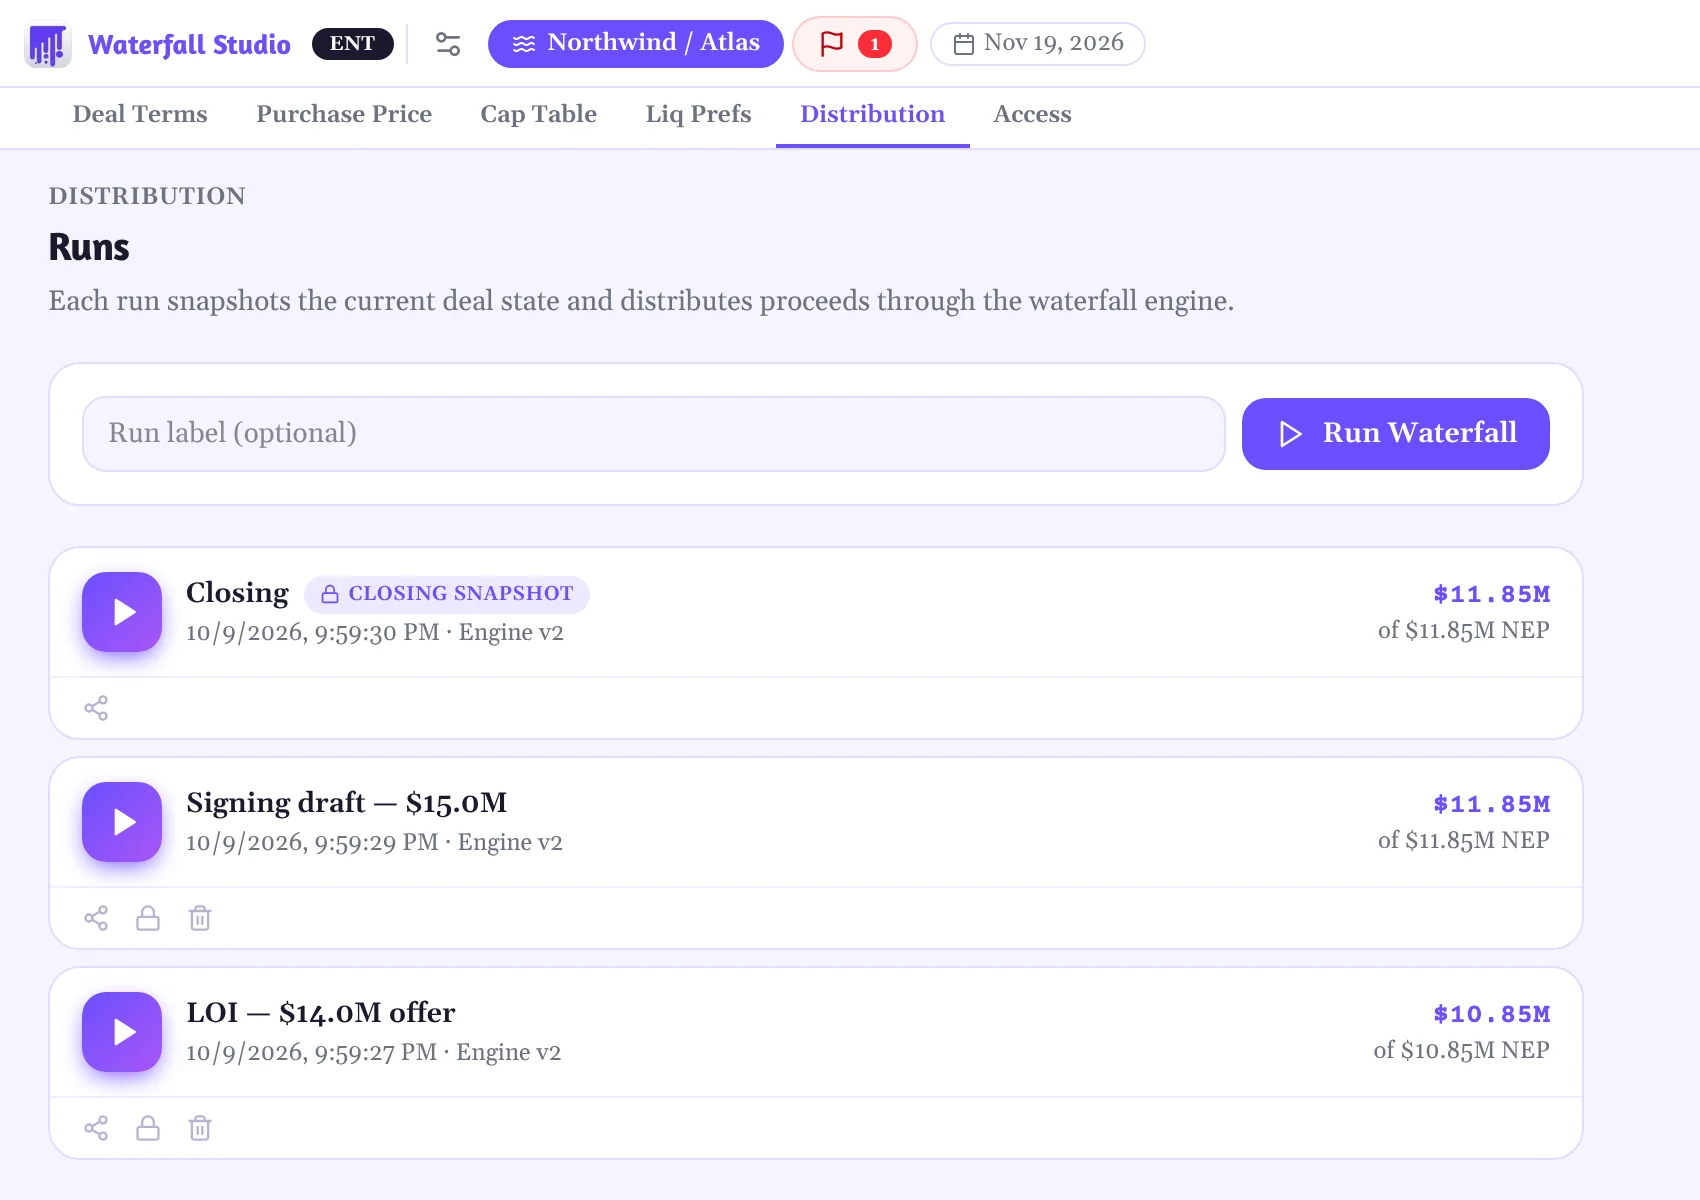
The Runs list in Studio with three versions: 'LOI — $14.0M offer' at $10.85M, 'Signing draft — $15.0M' at $11.85M, and 'Closing' at $11.85M marked as a locked closing snapshot.

“Every redline moves the payouts, and nobody sees it until closing.”

Who it's for

The same problem, asked three ways.

Sell-side advisors

Bankers, M&A advisors, fractional CFOs

“The buyer came back at $14M. What does that do to the founders versus $15M?”

LOI, signing and closing runs side by side, each kept exactly as computed.

Company counsel

Deal and venture attorneys for the company

“Is it worth fighting for non-participating Series A?”

The dollar value of each concession before you spend a turn on it.

The company

Founders, the CFO, the board, employees

“What did we give up between the LOI and the final agreement?”

Every version, labeled, with the date the terms last changed.

Why use Merger Waterfall for this

What you see in the product.

01

A version for every turn

Each run freezes the terms and the result together. Label them as the deal moves: LOI, signing draft, closing.

  • Inputs and results stored together
  • Engine version stamped on every run
  • Any version can be presented, shared or exported
Distribution · Runs
The Runs list in Studio with three versions: 'LOI — $14.0M offer' at $10.85M, 'Signing draft — $15.0M' at $11.85M, and 'Closing' at $11.85M marked as a locked closing snapshot.

02

Go back to what was proposed

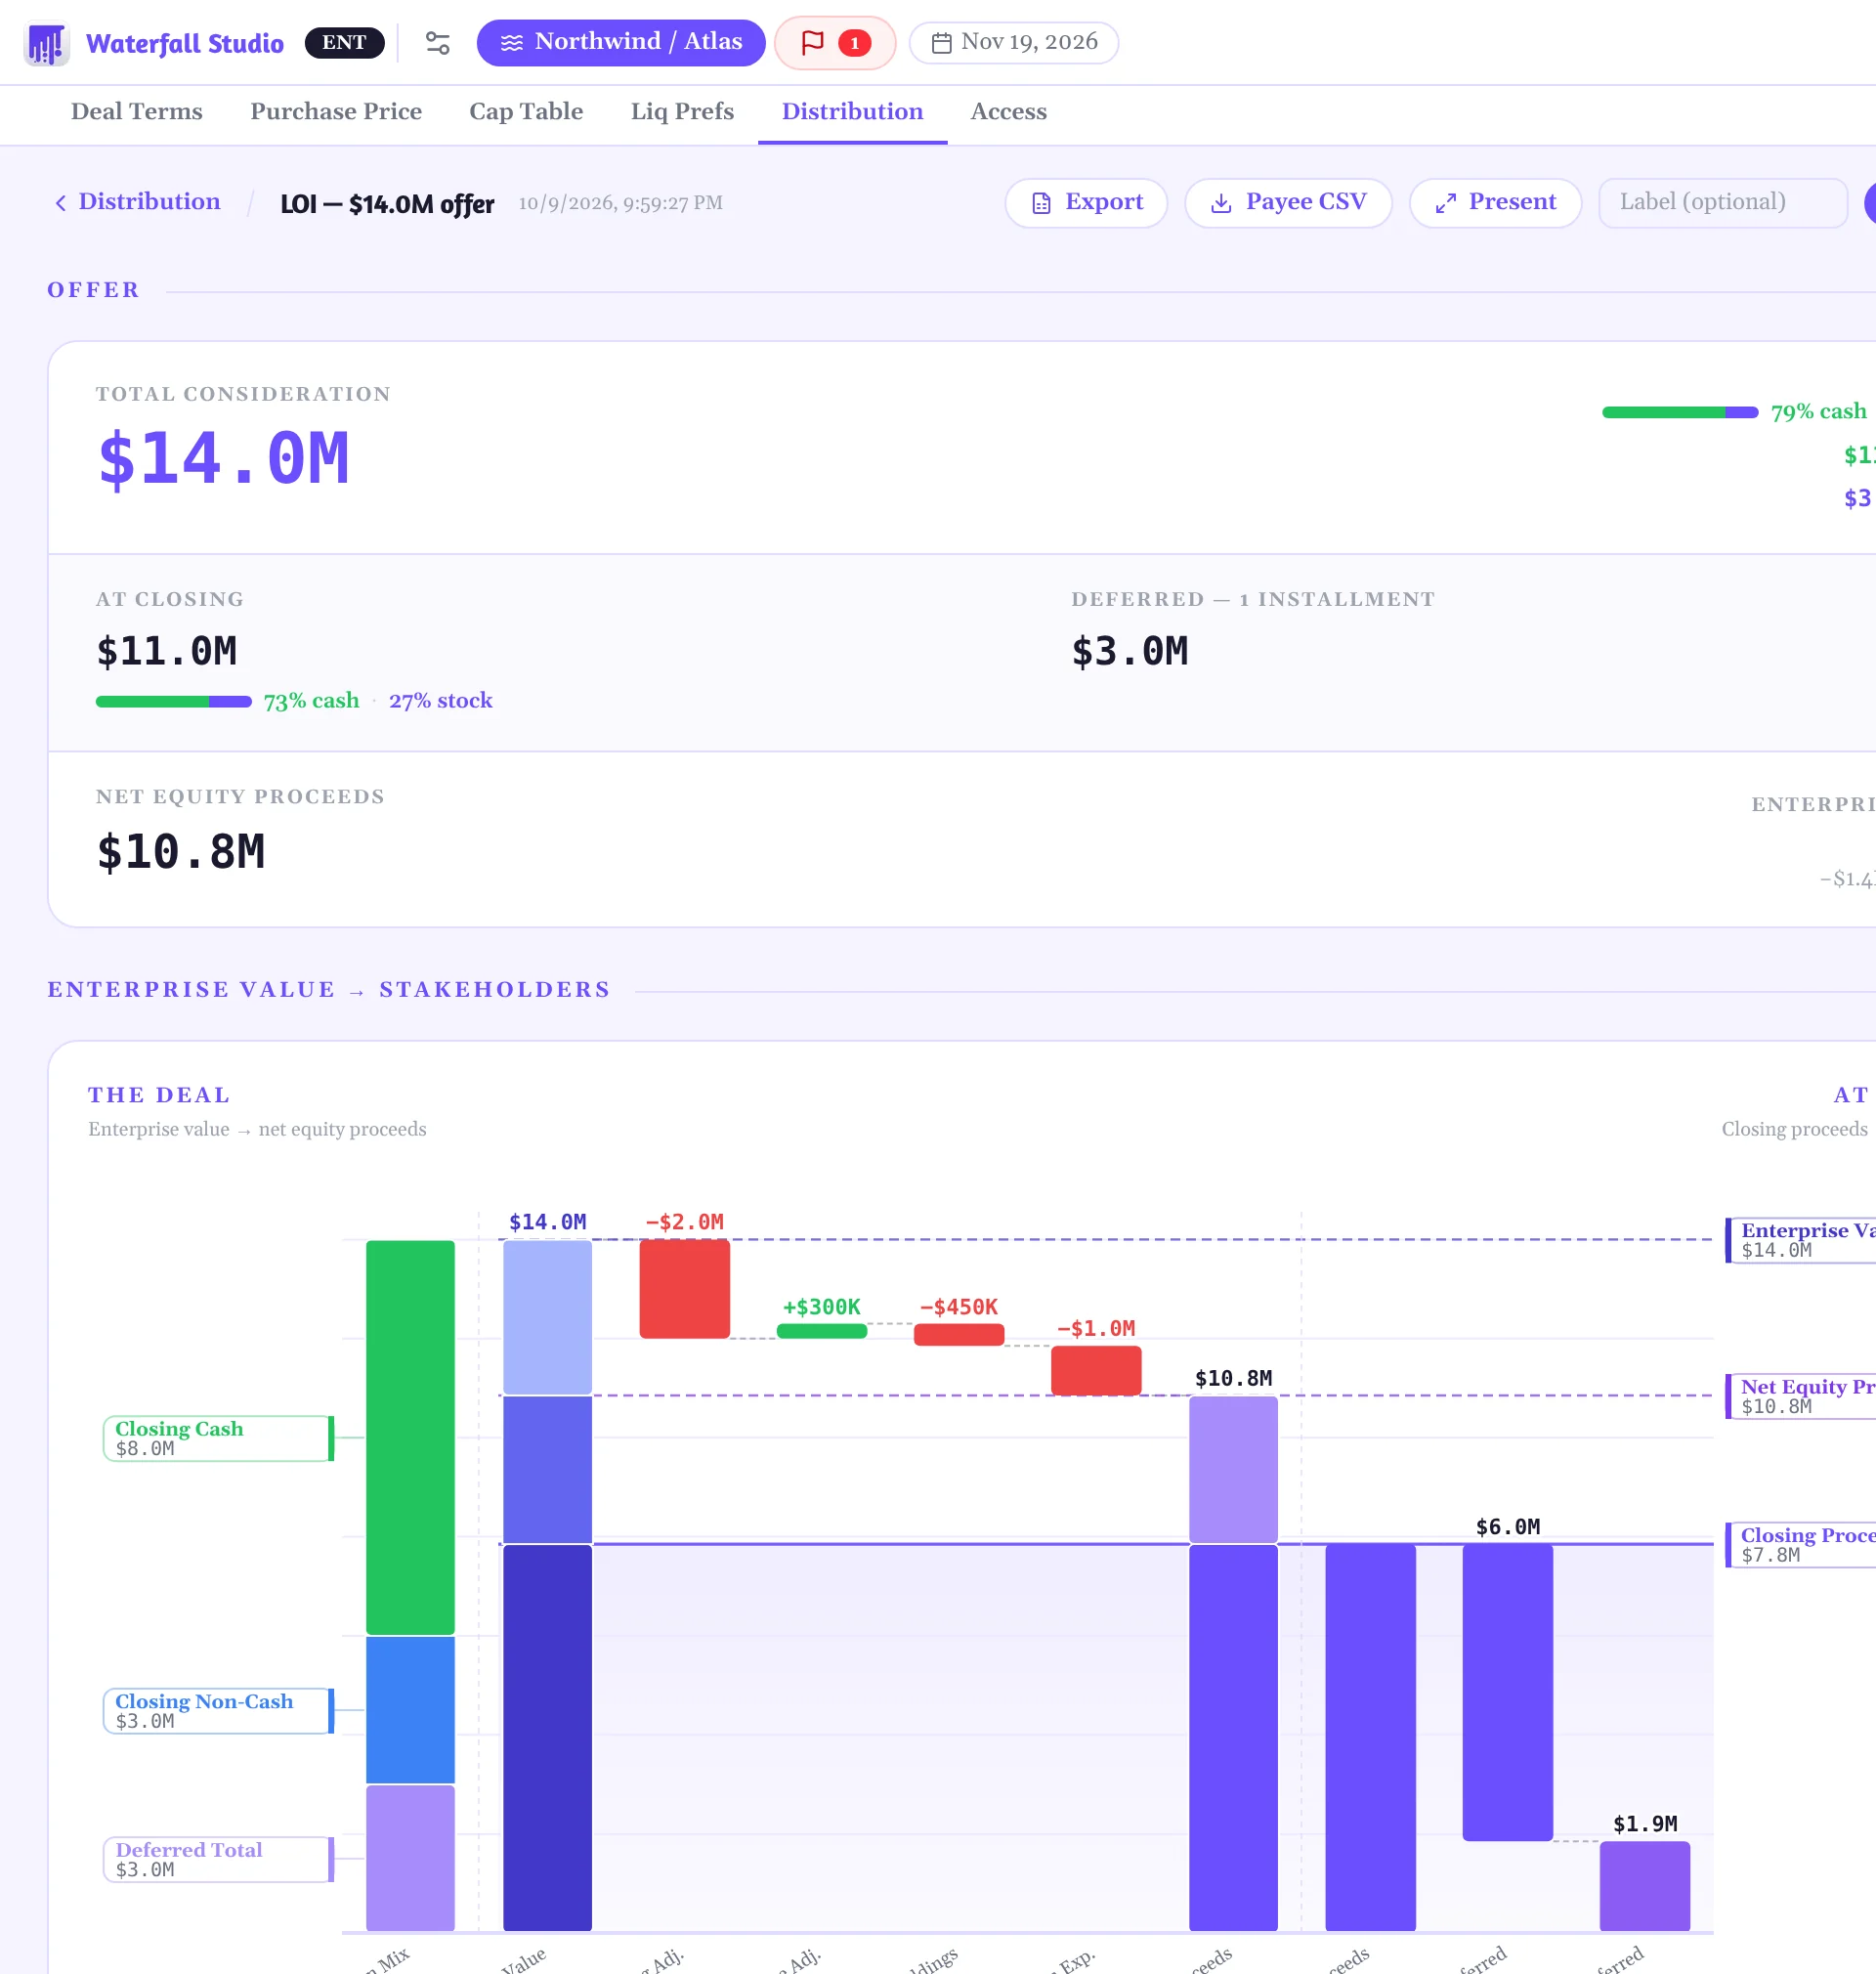
Reopen an earlier run and it reads exactly as it did the day it was computed, whatever has changed since.

  • The $14.0M LOI run still shows its $10.85M of net proceeds
  • Later edits never reach back into earlier runs
Distribution · an earlier run, reopened
The earlier 'LOI — $14.0M offer' run reopened in Studio: $14.0M total consideration, $10.8M net equity proceeds and its own waterfall chart.

03

Know the moment terms move on

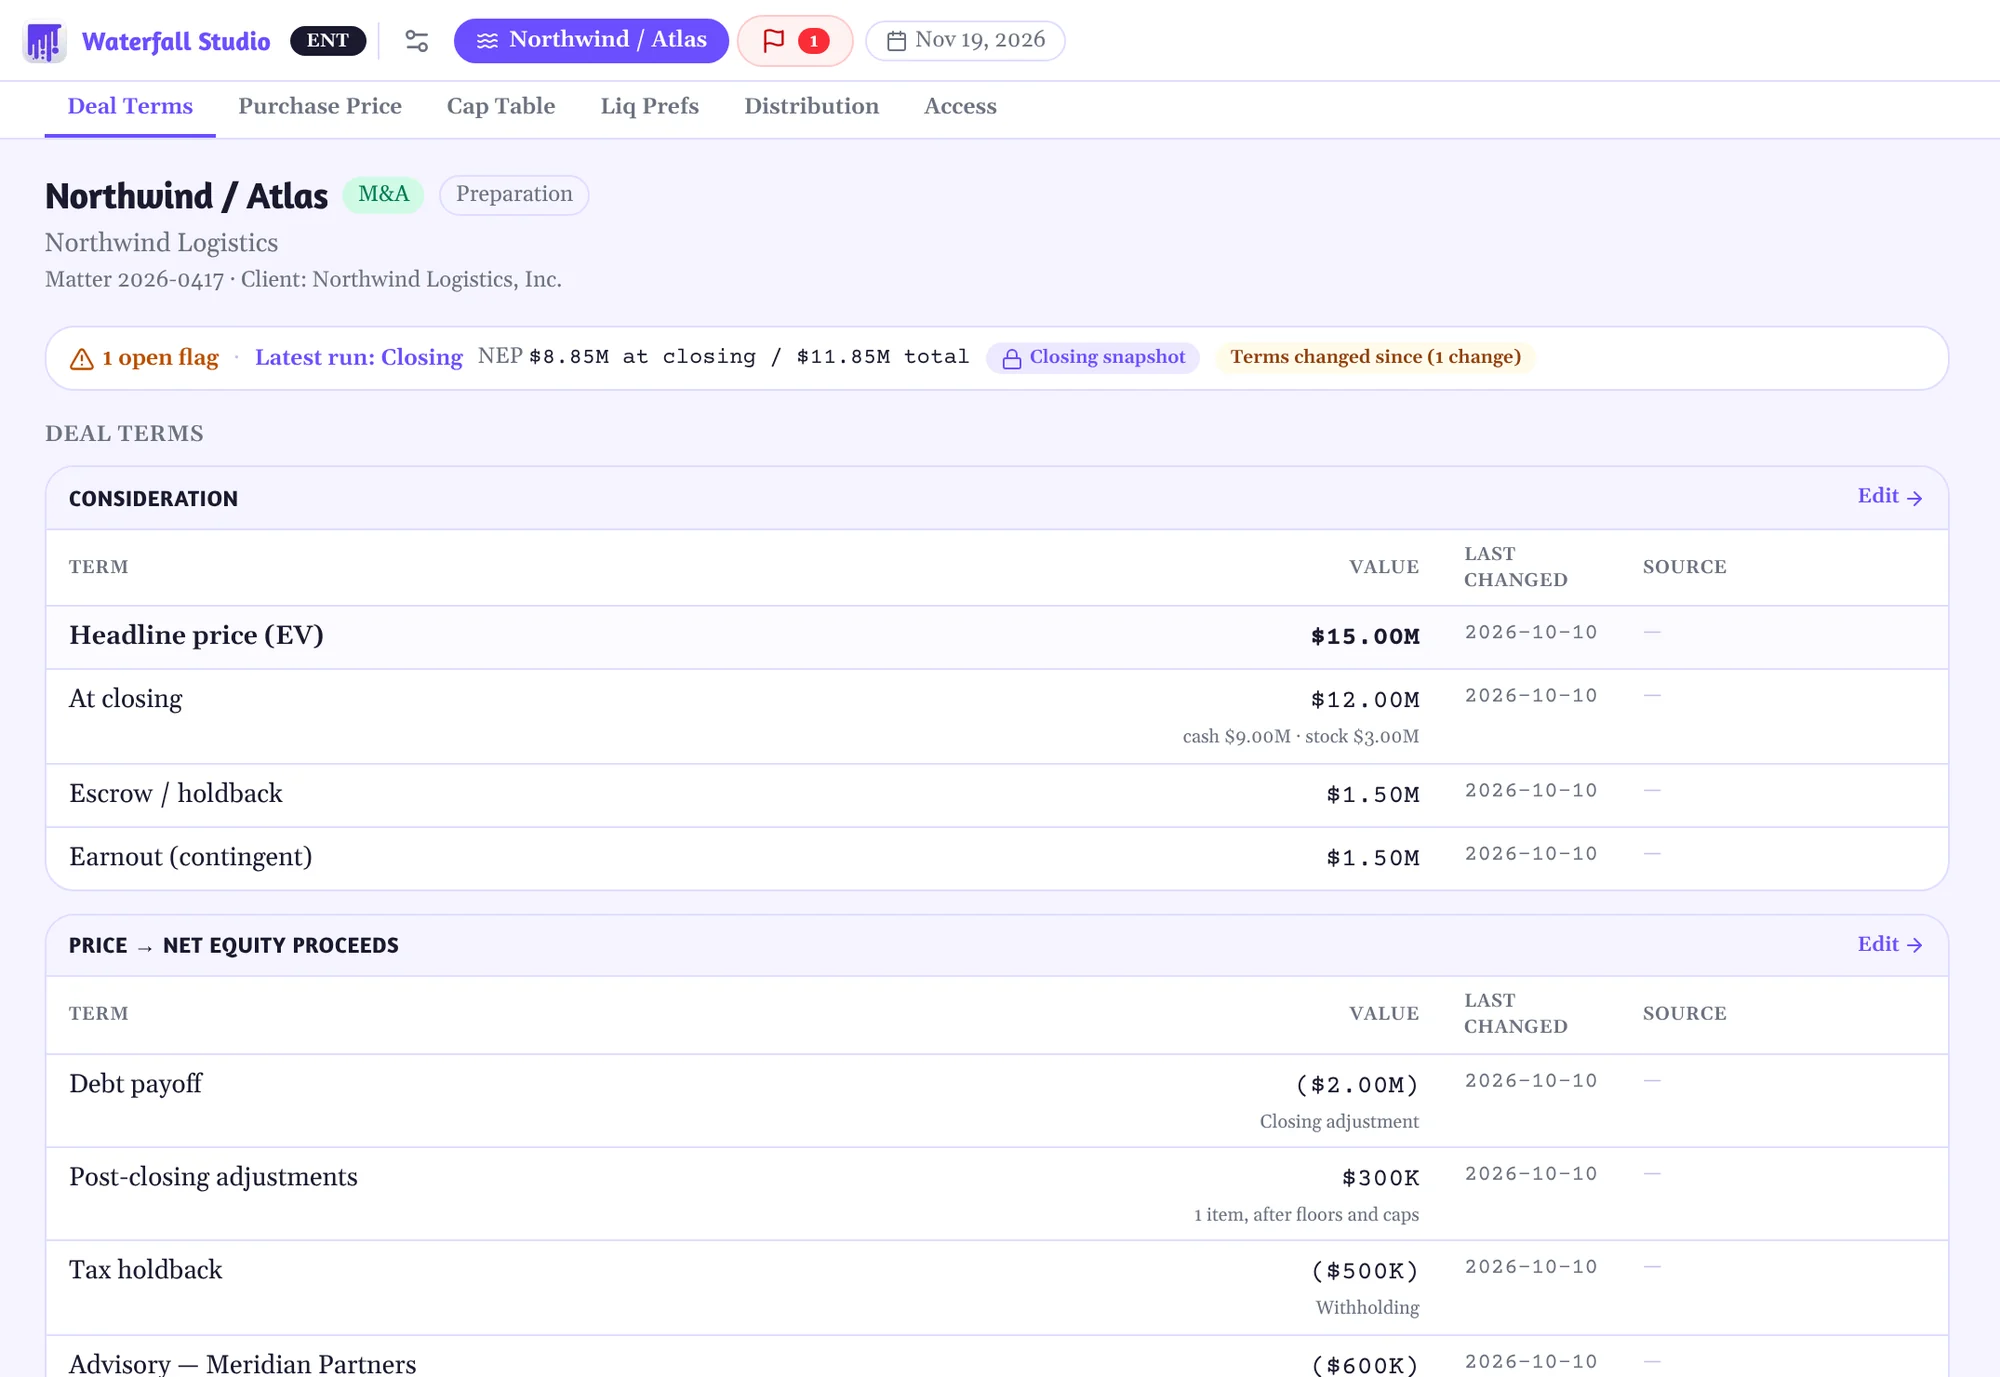
Change a term after a run and Deal Terms says so, with a count of what changed. Nobody circulates numbers that no longer match the deal.

  • “Terms changed since” beside the latest run
  • Every term change dated, with its source
Deal Terms · status line
Deal Terms after the tax holdback was raised to $500K: the status line shows the latest run is the locked Closing snapshot and a badge reads 'Terms changed since (1 change)'.

04

Ask your assistant what a change does

Connect Claude, ChatGPT or your own agent to the engine and ask what-if questions in plain English. The numbers come from the same deterministic engine, not from a language model.

  • Remote MCP server and REST endpoint
  • Deal data computed and returned, not stored
  • Enterprise plan, opening soon
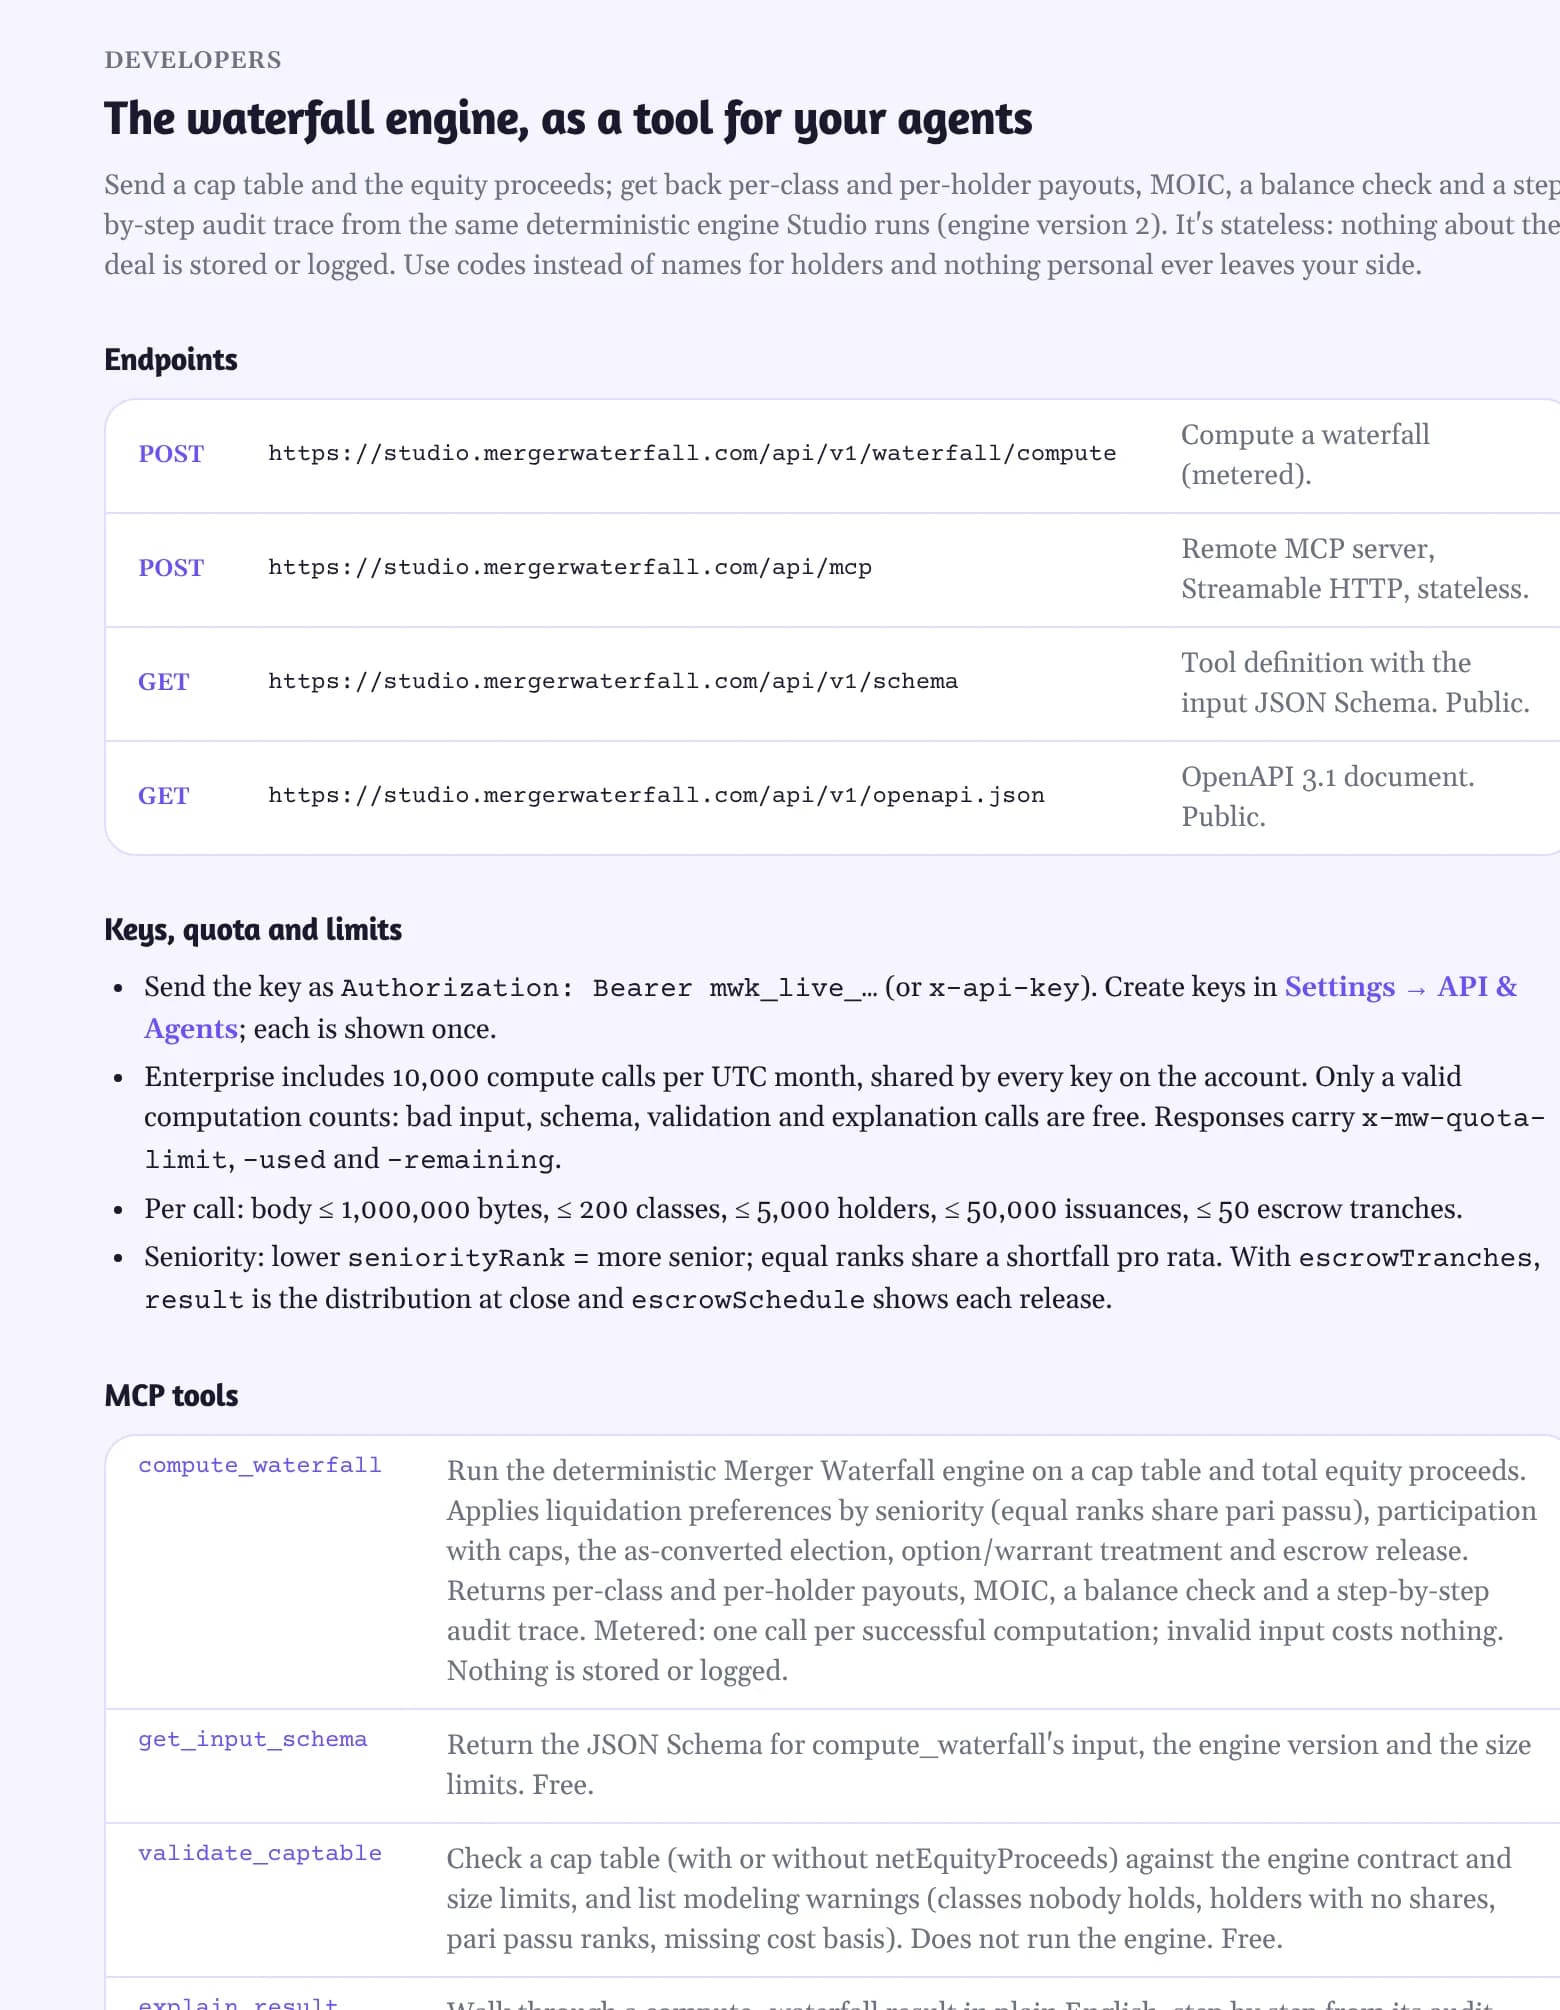
Developers · Endpoints and MCP tools
Studio's developer page listing the endpoints, the quota and limits, and the four MCP tools: compute_waterfall, get_input_schema, validate_captable and explain_result.

Deal scenarios

Where this comes up, with the numbers.

Each scenario changes one thing on the Northwind / Atlas demo deal and shows what every holder receives before and after. Computed by the same engine Studio runs.

Scenario 1LOI → signingDemo · Northwind / Atlas

The price went up $1M. What does that do for us?

What changed
LOI at $14.0M; signed at $15.0M (+7%)
Usually raised by
Sell-side advisor, reporting the buyer's revised offer

A 7% higher price more than doubles the founders' proceeds: Dana goes from $283k to $617k. Series B, already paid in full, does not move.

HolderLOI · $14.0MSigned · $15.0MChange
Meridian Ventures II

Series B lead

$6.00M$6.00M—
Cardinal Capital

Series A fund

$4.21M$4.46M+$250k
Dana Reyes

Founder · CEO

$283k$617k+$333k
Sam Okoro

Founder · CTO

$213k$463k+$250k
Employee RSAs

Common pool

$70.83k$154k+$83.33k
Option Holders

ITM options

$70.83k$154k+$83.33k
Net equity proceeds$10.85M$11.85M$1.00M

Why: The extra $1M arrives after the preferences are covered, so it is shared by the participating Series A, common and the option holders.

Computed by the Merger Waterfall engine · every column ties to its proceeds

Scenario 2FinancingDemo · Northwind / Atlas

The new investor wants a 1.5x preference. What does that cost us later?

What changed
Series B liquidation preference 1.0x → 1.5x
Usually raised by
An investor, in a financing or a bridge, months before any sale

In a $15M sale, a 1.5x Series B preference takes everything that would have gone to common: Dana's $617k becomes $0, and every employee holder is wiped out too.

HolderSeries B at 1.0xSeries B at 1.5xChange
Meridian Ventures II

Series B lead

$6.00M$9.00M+$3.00M
Cardinal Capital

Series A fund

$4.46M$2.85M−$1.61M
Dana Reyes

Founder · CEO

$617k—−$617k
Sam Okoro

Founder · CTO

$463k—−$463k
Employee RSAs

Common pool

$154k—−$154k
Option Holders

ITM options

$154k—−$154k
Net equity proceeds$11.85M$11.85M—

Why: The extra 0.5x adds $3M to the most senior claim. Series B and Series A then need $13M, more than the $11.85M available.

Computed by the Merger Waterfall engine · every column ties to its proceeds

Scenario 3FinancingDemo · Northwind / Atlas

If we push back on Series A participation, how much do we get back?

What changed
Series A: participating, capped at 2.0x → non-participating
Usually raised by
Company counsel, marking up the investor's terms

Removing Series A participation moves $463k from Cardinal Capital to common. Dana's proceeds rise from $617k to $822k.

HolderParticipating, 2.0x capNon-participatingChange
Meridian Ventures II

Series B lead

$6.00M$6.00M—
Cardinal Capital

Series A fund

$4.46M$4.00M−$463k
Dana Reyes

Founder · CEO

$617k$822k+$206k
Sam Okoro

Founder · CTO

$463k$617k+$154k
Employee RSAs

Common pool

$154k$206k+$51.39k
Option Holders

ITM options

$154k$206k+$51.39k
Net equity proceeds$11.85M$11.85M—

Why: Non-participating preferred takes its preference or its as-converted share, not both. At this price Series A keeps its $4M preference and stops sharing in the rest.

Computed by the Merger Waterfall engine · every column ties to its proceeds

Scenario 4Signing → closingDemo · Northwind / Atlas

The buyer raised the tax holdback. Who pays for it?

What changed
Tax withholding $450k → $500k
Usually raised by
Buyer's counsel, in the last turn of the purchase agreement

The extra $50k comes entirely out of the junior holders: Series A participation, common and options. Dana gives up $16,667; Series B is untouched.

HolderHoldback $450kHoldback $500kChange
Meridian Ventures II

Series B lead

$6.00M$6.00M—
Cardinal Capital

Series A fund

$4.46M$4.45M−$12,500
Dana Reyes

Founder · CEO

$617k$600k−$16,667
Sam Okoro

Founder · CTO

$463k$450k−$12,500
Employee RSAs

Common pool

$154k$150k−$4,167
Option Holders

ITM options

$154k$150k−$4,167
Net equity proceeds$11.85M$11.80M-$50.00k

Why: A deduction reduces net equity proceeds from the bottom of the waterfall up, so junior holders absorb it first.

Computed by the Merger Waterfall engine · every column ties to its proceeds

Try it on your next deal.

Bring the cap table export and the charter. Leave with a distribution spreadsheet you can hand to the board, the buyer and the auditor.